Construction Loans Explained
Quick Answer
A construction loan isn't a regular mortgage with a different name. It's a fundamentally different kind of financing, built around a home that doesn't exist yet. Instead of one lump sum at closing, funds are released in stages as the home is built, and the terms, equity requirements, and approval process usually look different from what you'd expect buying an existing home. The mechanics are worth understanding before you talk to a lender, not after.
What You'll Learn
- How construction loans differ from a standard resale mortgage
- The two basic structures: construction-to-permanent versus standalone construction loans
- How the draw schedule works, and why it matters for change orders
- Questions worth asking your lender directly, rather than assuming
Tim's Take
I've watched buyers go into a construction loan expecting it to feel like a regular mortgage application, and it catches them off guard when it doesn't. The down payment and equity requirements can look different than what you're used to, the approval process usually looks at the builder as well as you, and the money doesn't show up all at once. It's released in pieces as the work gets done. None of that makes it a bad process. It just means it's worth understanding the shape of it before you're in the middle of it.
Why the Common Assumption Is Wrong
Most buyers assume financing a new build works the same way as financing a home that already exists. Apply, get approved, close, done. A construction loan usually adds several layers to that: the lender is financing a project, not a finished asset, so the process tends to involve appraising a future completed value, reviewing the builder, and releasing funds progressively rather than all at once. That's a different kind of underwriting, and it's worth going in with realistic expectations.
How Construction Loans Work
Construction-to-Permanent vs. Standalone Construction Loans
Broadly, there are two structures. A construction-to-permanent loan (sometimes called a single-close loan) combines the construction financing and the eventual mortgage into one loan with one closing. Once the home is finished, it converts into a standard mortgage. A standalone construction loan is a separate, shorter-term loan just for the build, which you then pay off by refinancing into a permanent mortgage once construction is complete. A second closing, with its own costs and its own approval process. Ask your lender directly which structure they're offering and what the tradeoffs are for your situation.
Down Payment, Equity, and Land Value
Down payment and equity requirements for construction loans vary by lender, loan program, and your own financial picture. There's no single standard here. If you already own the lot outright, or have meaningful equity in land you're building on, that land equity can sometimes count toward your required down payment or equity contribution, which changes how much cash you actually need to bring to the table. Ask your lender directly how they treat land equity in your situation, rather than assuming a construction loan requires more cash down than a resale mortgage would. Sometimes it does, sometimes existing land equity offsets some or all of that difference.
The Draw Schedule
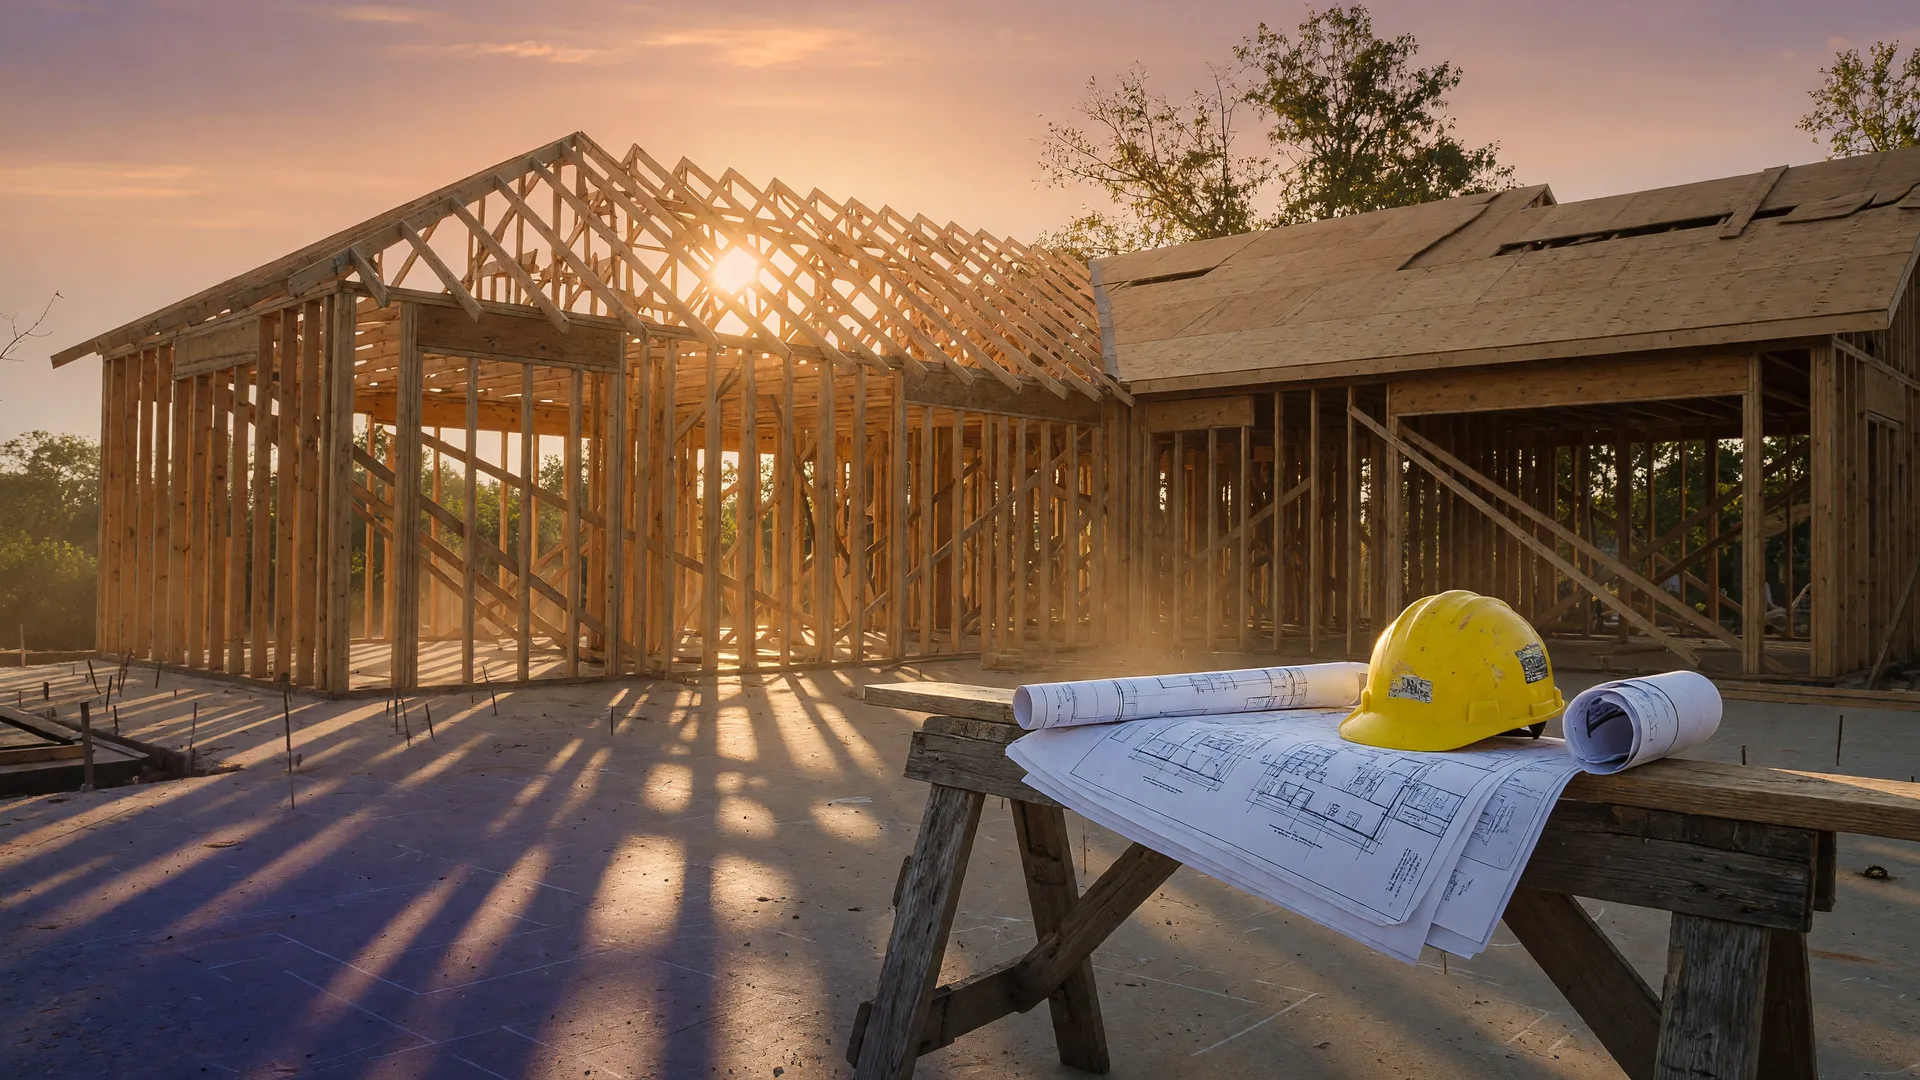
Instead of receiving the full loan amount at closing, funds are typically released in stages, called draws, tied to construction milestones (foundation, framing, drywall, and so on). Each draw is typically released only after the lender, often through their own inspector or appraiser, verifies that the corresponding stage of construction has been completed. That lender draw inspection is a separate process from any inspection you arrange yourself as the buyer. It confirms the work is far enough along to justify releasing funds to the builder, and isn't a substitute for your own independent inspection of the home's quality or condition. This is worth understanding alongside your builder contract's change order terms: if a change order adds cost mid-build, ask both your builder and your lender how that's handled within the draw schedule, since it can affect timing as much as it affects the total amount.
Interest During Construction
Many construction loans charge interest only on the amount actually drawn so far, not the full loan amount, so your payments may increase as more of the loan is disbursed throughout the build. Confirm with your lender exactly how this is calculated for your specific loan.
Builder Approval
Because the lender is financing a project that depends on the builder actually completing it, many lenders review and approve the builder separately from approving you as the borrower. If you're working with a smaller or newer builder, it's worth confirming early in the process that your chosen lender will work with them.
Applying Evidence Over Opinion to Construction Financing
Construction loan terms vary meaningfully by lender, loan program, and even by builder, which makes this an area where a general rule of thumb can lead you astray. Rather than relying on what a friend's construction loan looked like, or a number you saw online, ask your own lender directly:
- What's the actual down payment or equity requirement for this specific loan program, and how is land equity treated?
- How exactly is the draw schedule structured, and who verifies each draw?
- How is interest calculated during the construction period?
- What happens to financing if a change order increases the project cost mid-build?
A specific answer from your lender, in writing, is worth more than a general assumption about how construction loans work.
Frequently Asked Questions
Is a construction loan the same thing as a regular mortgage?
Not exactly. Some construction-to-permanent loans do convert into a standard mortgage once the home is finished, but the construction phase itself is structured differently: draws instead of a lump sum, interest calculated on the drawn amount, and often a separate review of the builder. For the specific terms, rates, and qualification requirements that apply to you, that's a conversation for your loan officer. I can help you think through the building process and the timeline from a buyer's-agent perspective, but the lending details are their expertise, not mine.
Do I need a bigger down payment for a construction loan?
It depends on the lender, the loan program, and your own financial picture. There's no single rule here. Some construction loans do require more down than a comparable resale mortgage; others may require less if you're bringing meaningful equity from land you already own. Confirm the specific requirement with your lender early, rather than assuming a general rule applies to your situation.
Can I use my construction loan to cover a change order?
That depends on your specific loan and how your draw schedule is structured. This is exactly the kind of question to ask your lender directly, ideally before you're mid-build and facing a change order you weren't expecting.
What happens if the home costs more to build than the loan covers?
This depends heavily on your lender and loan program. A contingency reserve for cost overruns may be available under some loan programs, but it isn't a standard feature of every construction loan, so don't assume one exists in yours. Ask your lender specifically how cost overruns are handled under your loan terms before you sign.
Bottom Line
A construction loan runs on different mechanics than the mortgage you'd use to buy an existing home. The equity requirements, the draw schedule, and the builder approval process are all worth understanding upfront. The details vary by lender and loan program, so the right move is asking your own lender specific questions rather than relying on a general idea of how construction loans work.
If you're getting ready to build in Louisville and haven't engaged your own agent yet, I can help you think through the building process, the timeline, and how it fits together with your builder contract, from a buyer's perspective, alongside your lender's guidance on the loan itself. How buyer-agent compensation is handled can vary by builder and transaction, so that's something we'll establish clearly upfront as part of your representation agreement.
If you'd like to talk before you get too far into the process, call 502-429-3866.
- Tim
About Tim Hollinden
Tim Hollinden is a former home builder and Broker Associate with The Hollinden Team at eXp Realty. For more than 24 years, he has completed over 1,650 real estate transactions throughout Greater Louisville by combining builder knowledge with practical, evidence-based real estate advice.